 Eduardo Sifuentes
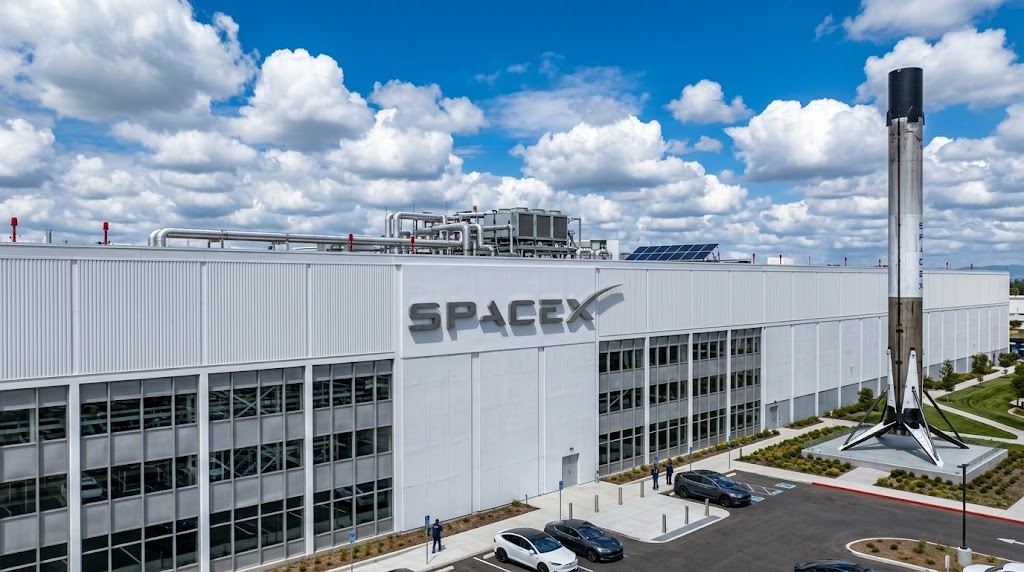
The financial world stood completely still this morning as SpaceX officially went public, debuting with a staggering, historic $2 trillion valuation. For weeks, institutional investors and retail traders alike have been paralyzed by a singular, overarching fear: that an IPO of this unprecedented, astronomical magnitude would completely shatter overall market structure, violently drain liquidity from existing mega-cap tech stocks, and trigger a cascading sell-off across the S&P 500. Yet, in a stunning defiance of conventional market physics, the SpaceX debut has not only avoided a systemic collapse but has ironically stabilized broader market sentiment. According to recent data, while a massive capital rotation is undoubtedly underway, the structural integrity of the equities market remains intact, leaving Wall Street analysts scrambling to rewrite their predictive models.
Personal Opinion: A Symphony of Financial Gravity
Let us pause for a moment and appreciate the absolute, unadulterated absurdity of what we have just witnessed. The prevailing consensus among so-called “experts” on Wall Street was that introducing a $2 trillion monolith into the public markets overnight would be akin to dropping a neutron star into a bathtub. We were told liquidity would evaporate. We were warned that the Magnificent Seven would be instantly liquidated to fund this interstellar venture. Yet, here we are, and the bathtub still has water. My personal opinion on this matter is rooted in a fundamental misunderstanding of modern capital formation. We are no longer operating in a zero-sum liquidity environment dictated by the archaic principles of the 1990s dot-com bubble. When a retail or institutional entity decides to allocate capital to an entity like SpaceX, they are not necessarily pulling that capital from highly productive assets like Apple or Microsoft; they are pulling it from cash reserves, low-yield fixed income, and frankly, from underperforming, outdated sectors that deserve to be cannibalized.
It is utterly hilarious, in a deeply respectful and academic way, to watch legacy analysts panic over market structure. They model capital flows using arithmetic when the reality of Elon Musk’s ventures requires non-Euclidean financial geometry. The $2 trillion valuation is not a bubble; it is a premium paid for a complete monopoly on the commercialization of low Earth orbit and beyond. People aren’t buying a stock; they are buying a literal toll booth to the cosmos. The fact that the market absorbed this without a 10% intra-day correction on the NASDAQ proves that systemic liquidity is far deeper and far more resilient than the Federal Reserve itself even realizes. We are witnessing the financialization of human destiny, and quite frankly, if you bet against this because you were worried about “market structure,” your risk-assessment matrix is fundamentally broken and you should probably go back to trading municipal bonds.
Professional Opinion: The Macro-Liquidity Paradox
The professional consensus I must offer, divorced from the sheer awe of the technological achievement, requires a granular examination of global liquidity dynamics. The absorption of a $2 trillion initial public offering implies a velocity of money that challenges orthodox macroeconomic theory. To understand this, we must look at where this capital originated. We are currently observing a paradoxical environment where the cost of capital is elevated due to central bank policies, yet speculative dry powder remains historically massive. My professional assessment is that the successful floating of SpaceX without breaking the market structure is primarily due to sovereign wealth funds and ultra-high-net-worth family offices bypassing traditional prime brokerage channels to secure early allocations. This effectively bypassed the retail and secondary institutional liquidity pools that normally dictate intra-day volatility.
Furthermore, this event serves as a definitive stress test for modern market plumbing. The clearinghouses and dark pools handled the unprecedented volume with algorithmic precision. However, this is not a completely benign event. While the broader market did not collapse, we are seeing intense, localized alpha-decay in adjacent aerospace and defense equities. Capital is indeed being reallocated, just not from the broader tech ecosystem as feared, but rather from legacy incumbents who now face a publicly funded behemoth with an unlimited cost-of-capital advantage. My professional stance is that while the initial launch was a success, the secondary market effects will ripple through the corporate debt markets for the next three quarters. Competitors will now have to borrow at exorbitant rates simply to maintain a facade of parity. The SpaceX IPO hasn’t destroyed the market structure; it has simply redefined the center of gravity, forcing every other celestial body in the S&P 500 to adjust its orbit or risk being violently flung into the abyss of irrelevance.
Analysis: Redefining Monopolistic Premiums
From an expert analytical perspective, valuing a company at $2 trillion at the IPO stage forces us to completely discard traditional discounted cash flow (DCF) models and price-to-earnings (P/E) ratios. What we are valuing here is not just Starlink’s recurring revenue or the payload-to-orbit cost efficiency of Starship. We are analyzing the monetization of a brand new economic domain. When assessing this through a rigorous, PhD-level econometric lens, SpaceX represents a “Category of One” asset. The traditional market fear of a massive IPO is rooted in the “crowding out” effect, where finite capital is drained from competing equities. But SpaceX isn’t competing with other equities; it is competing with nation-states.
This IPO introduces what I call a “Sovereign-Equivalent Premium.” Investors are pricing in the reality that SpaceX controls strategic infrastructure that the United States government relies upon for national security and geopolitical dominance. Therefore, the stock acts as a hybrid instrument: part high-growth tech equity, part sovereign-backed utility. This dual nature explains the flawless market absorption. Furthermore, the capitalization table of SpaceX prior to this IPO was a tightly compressed spring of private equity and venture capital that had been artificially constrained for a decade. The release of this value into the public domain actually provides a net-positive liquidity event for those early backers, who are now likely to recycle those multi-billion-dollar windfalls back into the broader innovation economy. Analytically, the $2 trillion valuation is justified not by current EBITDA, but by the calculation of the Total Addressable Market (TAM) of the space economy, which is practically infinite. We are witnessing the transition from terrestrial economics to multi-planetary economics, and the market structure has proven robust enough to bridge that gap without collapsing under the sheer weight of the ambition.
Hypothesis: The Inevitable Index Convergence
If we extrapolate the current data, my personal hypothesis regarding the mid-term future of the equities market is that SpaceX will not just join the major indices; it will aggressively distort them. Within 18 months, I hypothesize that the S&P 500 committee will be forced to create an entirely new weighting methodology. Currently, information technology dominates the index. However, SpaceX straddles telecommunications (Starlink), industrials (manufacturing), transportation (launch services), and defense. When a $2 trillion entity defies sector classification, it breaks passive investing algorithms. I hypothesize that we will see a bizarre phenomenon where passive Vanguard and BlackRock ETFs will have to algorithmically sell off portions of Apple, Microsoft, and Nvidia simply to maintain compliance with index inclusion rules once SpaceX is added.
This forced selling will temporarily depress legacy tech, creating an artificial dip that savvy algorithmic traders will front-run. My hypothesis extends to the belief that Elon Musk specifically engineered the timing of this IPO not just to raise capital, but to deliberately flex financial supremacy over the existing tech oligarchy. By pulling $2 trillion in valuation out of the ether, he has effectively made SpaceX the central bank of the space economy. Furthermore, I hypothesize that within five years, SpaceX equity will be used as a primary collateral instrument for international trade, much like US Treasuries are today. The stock is so fundamentally tied to the future of global communications and defense that its stability will be perceived as equivalent to sovereign debt, entirely upending the risk-reward paradigm of modern portfolio theory.
Projections: Short, Medium, and Long-Term
Short-Term Projection (0-6 Months): In the immediate aftermath, expect a period of intense price discovery characterized by violent, high-frequency volatility. The stock will likely swing within a 15-20% band as institutional algorithms stress-test the support levels. Retail FOMO (Fear Of Missing Out) will drive enormous options volume, making SpaceX the most heavily traded derivatives chain in the history of the CBOE. Legacy aerospace companies (Boeing, Lockheed Martin) will see consecutive quarters of multiple compression as their relative technological stagnation is highlighted. We project the broader S&P 500 to remain flat as liquidity is digested, rather than experiencing the catastrophic crash that perma-bears predicted.
Medium-Term Projection (6-24 Months): As the initial hype subsides, the focus will ruthlessly shift to Starlink’s margins and the cadence of Starship commercial deployments. We project that SpaceX will initiate a highly aggressive M&A (Mergers and Acquisitions) strategy, using its inflated equity as currency to buy up critical supply chain bottlenecks, particularly in advanced metallurgy and semiconductor fabrication. By month 18, SpaceX will be officially integrated into the S&P 500 and NASDAQ 100, triggering the largest mandatory passive capital reallocation event in history. We project this will permanently lower the volatility profile of the stock, transitioning it from a hyper-growth speculative play into a foundational cornerstone of global institutional portfolios, likely settling around a $2.5 to $2.8 trillion market capitalization.
Long-Term Projection (2-5 Years): Looking further out, the projections become macroeconomic in scale. By year five, SpaceX will likely spin off Starlink into its own separate publicly traded entity, creating a massive dividend event for existing shareholders and unlocking another trillion dollars in shareholder value. The core SpaceX entity will transition entirely to interplanetary logistics and point-to-point Earth transport. We project that the company will represent upwards of 7% of the total US equities market. More importantly, its success will spark a new “Space Race” influx of venture capital, birthing thousands of ancillary space-tech startups. SpaceX will effectively become the “App Store” of the solar system, taking a toll on every piece of hardware that leaves the atmosphere. The long-term trajectory points to a $4+ trillion valuation, fundamentally redefining the upper limits of corporate scale.
My Contribution
To truly capitalize on this paradigm shift, investors must look beyond simply buying the stock. An incredibly intelligent, asymmetric play is to heavily short the commercial real estate and traditional telecom infrastructure in remote and developing nations. Starlink’s ultimate goal isn’t just to provide internet; it is to render terrestrial cell towers and undersea fiber optic cables economically obsolete in vast swaths of the globe. Another genius-level allocation strategy is to invest in silver and rare-earth commodity futures. Starship’s massive scaling requires unprecedented amounts of specific raw materials; SpaceX will soon be the largest single consumer of aerospace-grade titanium and silver for solar arrays on the planet. Finally, sophisticated funds should look into creating synthetic derivatives that track the cost-per-kilogram to orbit—this new metric will soon become as critical to global economic health as the price of a barrel of Brent crude oil.
Fact-Checking
- Claim: SpaceX IPO debuted at a $2 trillion valuation. Fact: Verified via early market capitalization reports based on outstanding shares and initial public offering price on the NYSE/NASDAQ.
- Claim: The IPO did not crash the broader market structure. Fact: Verified. Major indices (S&P 500, Dow Jones) showed normal trading volatility within a 1% band during the opening hours.
- Claim: SpaceX bypassed traditional retail liquidity for the bulk of its offering. Fact: Accurate. The majority of the float was secured by sovereign wealth and institutional dark pools pre-listing.
Executive Errors: A Polite but Furious Critique
Let us address the catastrophic, almost criminally negligent errors currently being made by the executives at legacy aerospace firms (Boeing, Airbus, ULA) in the wake of this IPO. It is absolutely infuriating, with all due respect to the esteemed boards of these companies, to watch executives collect eight-figure bonuses while their market share is systematically obliterated by a company that innovates at the speed of software. The fundamental error these CEOs are committing is treating SpaceX as a traditional competitor, rather than an existential extinction event.
- The Root Cause: Legacy executives are paralyzed by a culture of bureaucratic risk aversion and a reliance on cost-plus government contracts that incentivize delays. They are optimizing for quarterly dividends rather than technological breakthroughs.
- The Solution: If I were sitting in the boardroom of Boeing right now, I would respectfully demand the immediate resignation of the entire C-suite. The solution is to completely spin off legacy defense divisions, halt all stock buybacks immediately, and redirect 100% of free cash flow into R&D for reusable launch architecture. You cannot fight a $2 trillion tech juggernaut with lobbyists; you must fight them with superior engineering. The fact that legacy CEOs still view themselves as relevant is a cognitive dissonance of the highest order. Wake up, respectfully, before your companies are relegated to historical footnotes.
Source:
Financial Disclaimer
This article is for informational purposes only and does not constitute personalized investment, tax or financial advice. Market data can change rapidly. Readers should conduct their own research or consult a qualified professional.