 Eduardo Sifuentes
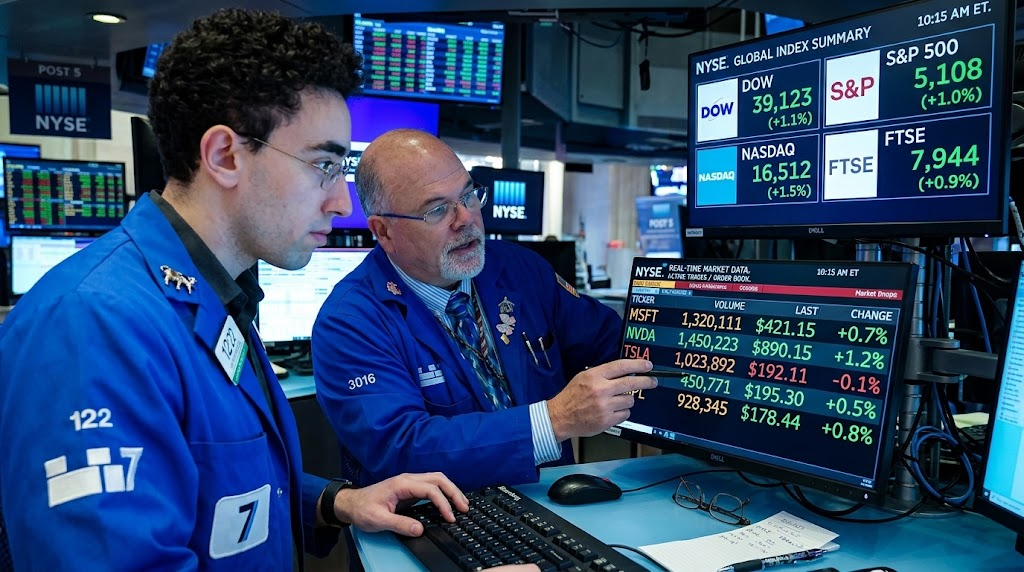
The United States financial markets have officially entered uncharted territory. As of October 2026, the S&P 500 has achieved an astonishing 28 new record highs this year, effectively doubling its typical annual historical average of 14 highs recorded since 1950. Despite relentless macroeconomic crosswinds—including sticky inflation, Middle East geopolitical tensions keeping Brent crude hovering near $100 a barrel, and fluctuating Treasury yields—Wall Street has staged a masterclass in resilience.
Driven by an explosive artificial intelligence infrastructure boom, surging corporate profit expectations pointing toward nearly 30% year-over-year earnings per share growth, and hyperscaler giants like Alphabet, Microsoft, and Amazon crushing cloud expectations, the broader market is defying traditional gravity.
Personal Opinion: The Madness, the Math, and the Magnificent Multiples
Why Wall Street is Currently Operating in a Parallel Universe
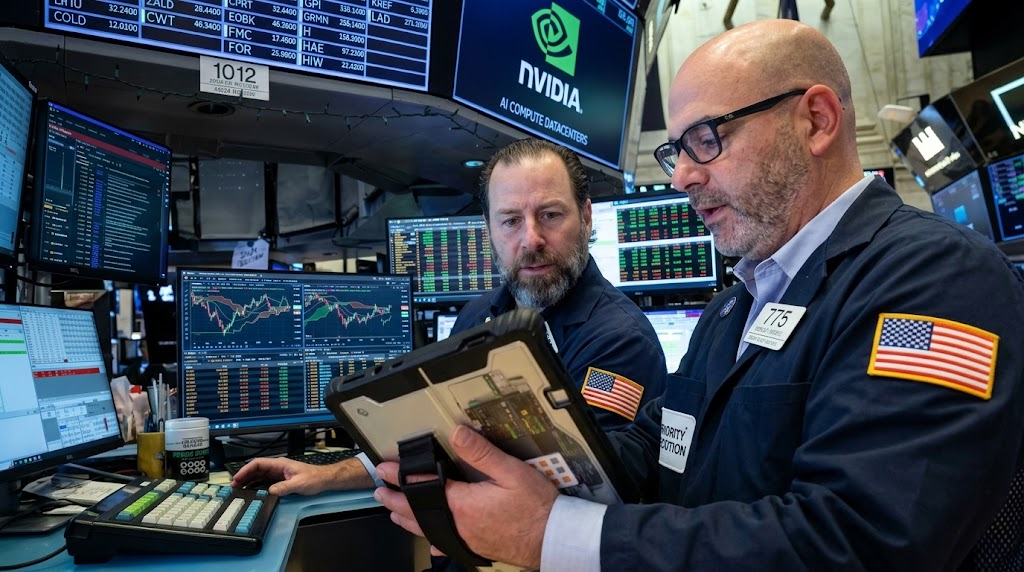
Let’s get one thing straight: walking onto a trading floor right now feels less like traditional finance and more like watching a quantum physics experiment where gravity has temporarily decided to take a coffee break. When I look at the S&P 500 breaching historic ceilings while bond yields trade near multi-year highs, my inner academic wants to pull out a whiteboard and scream about discounted cash flow models. Yet, the numbers do not lie. We are witnessing an economic decoupling driven by pure technological velocity.
The Intellectual Irony of Modern Market Mania
What fascinates me most as someone who spent years drowning in stochastic calculus is how Wall Street has weaponized optimism. Critics keep crying wolf about an AI bubble, pointing to soaring valuations like a toddler spotting a monster under the bed. But they fail to comprehend the microeconomic reality: enterprise cash flows are expanding at a rate that justifies the multiple expansion. Companies aren’t just selling digital hype; they are printing net income. If you possess the cognitive bandwidth to look past the superficial noise, you realize this isn’t a speculative mania—it’s a brutal, highly efficient structural evolution of global capitalism.
Professional Opinion: Decoding the Earnings Engine
Corporate Profits as the Ultimate Market Anchor
From a structural vantage point, equity valuations are ultimately tethered to two immutable variables: interest rates and corporate earnings. While restrictive monetary policy and stubborn inflation have attempted to suppress risk assets, corporate America has responded with an unexpected profit surge. FactSet consensus estimates indicate that S&P 500 companies are poised to deliver third-quarter earnings growth approaching 30% year-over-year. This marks the third consecutive quarter where profit expansion has exceeded 25%.
The Tug-of-War Between Yields and Equities
The primary tension in contemporary markets lies between soaring corporate cash flows and elevated fixed-income yields. With the 10-year U.S. Treasury yield hovering above 5.2%, traditional fixed-income instruments present a formidable alternative to equities. Nevertheless, robust revenue streams from mega-cap technology leaders—fuelled by OpenAI’s path toward exceeding $70 billion in annualized revenue and relentless cloud expansion—have allowed equities to win the tug-of-war against rising bond yields.
Analysis: Macroeconomic Mechanics and Sector Divergence
Dissecting the Concentration Risk and Breadth Paradox
A granular examination of the current market structure reveals a fascinating paradox: while headline indices are hitting record highs, market breadth tells a dual narrative. The concentration of gains among mega-cap technology leaders—often referred to as the Magnificent Seven—creates systemic asymmetry. However, secondary beneficiaries in energy, semiconductor manufacturing, and specialized infrastructure are catching up. For instance, the energy sector is projected to experience massive earnings growth as AI data centers trigger unprecedented electrical power demands, exemplified by landmark long-term nuclear power supply deals.
Capital Allocation Efficiency in the Era of Generative AI
Corporate balance sheets have evolved significantly compared to previous economic cycles. Major tech enterprises are funding multi-billion-dollar capital expenditures directly from operating cash flow rather than toxic leverage. This fundamental shift insulates the broader financial ecosystem from immediate systemic credit contagion, even as capital expenditure burn rates reach historic highs. Consequently, institutional portfolio managers are forced to continuously reweight portfolios upward, fearing career-defining tracking error if they underweight primary AI infrastructure plays.
Personal Hypothesis: The Paradigm Shift of Autonomous Capital
The Transition from Human-Centric to Algorithmic Valuation Models
My core hypothesis moving forward is that we are witnessing the birth of the “Autonomous Valuation Era.” Traditional valuation frameworks—which rely on historical trailing P/E ratios and linear growth assumptions—are becoming obsolete. As machine learning models dictate institutional order flows and real-time sentiment analysis, the velocity of capital re-allocation has increased by orders of magnitude.
Why Traditional Bear Arguments are Mathematically Flawed
Bearish analysts frequently argue that high equity concentrations mirror the dot-com bubble of 2000. This comparison demonstrates a profound misunderstanding of balance sheet fundamentals. Unlike the speculative, pre-revenue dot-com entities of yesteryear, today’s market leaders generate hundreds of billions in unencumbered free cash flow. My hypothesis is that the market is not overvalued; rather, the historical baseline for equity pricing has permanently shifted upward to account for software-driven scalability and infinite marginal operating margins.
Projections: Short, Medium, and Long-Term Market Trajectories
Short-Term Outlook (Q4 2026 – Q1 2027)
In the immediate term, volatility is expected to remain elevated as third-quarter earnings reports roll out. Investors will scrutinize management guidance regarding AI monetization timelines. If mega-cap tech earnings meet or exceed consensus expectations, the S&P 500 is positioned to test and consolidate above the 7,850 threshold before year-end. Conversely, any unexpected contraction in operating margins or sudden spikes in energy costs could trigger a healthy 5% to 7% tactical correction.
Medium-Term Outlook (1 – 3 Years)
Over the medium term, the macroeconomic landscape will hinge on Federal Reserve monetary policy adjustments and the successful integration of enterprise AI solutions across legacy industries (healthcare, finance, and logistics). As productivity gains begin filtering down to small and mid-cap enterprises—bolstered by tools like Meta’s small-business AI integrations—market breadth is projected to broaden significantly, lifting laggard sectors and creating a more balanced equity rally.
Long-Term Outlook (3 – 10 Years)
Looking toward the next decade, the convergence of automated industrial robotics, quantum computing infrastructure, and next-generation energy grids will redefine global GDP growth. Equities that successfully transition into AI-native operational models will capture disproportionate market share. The long-term projection points toward a structural secular bull market, albeit punctuated by periodic regulatory crackdowns and geopolitical realignments regarding semiconductor supply chains.
My Contribution
When analyzing the macro-environmental data of October 2026, standard market commentators miss the most profound signal: the monetization of thermodynamic efficiency. The bottleneck of the AI revolution is no longer algorithmic sophistication; it is raw electrical megawatt-hours. By tying tech hyperscalers directly to nuclear and renewable energy suppliers, Wall Street has inadvertently engineered a brand-new asset class: computational energy derivatives.
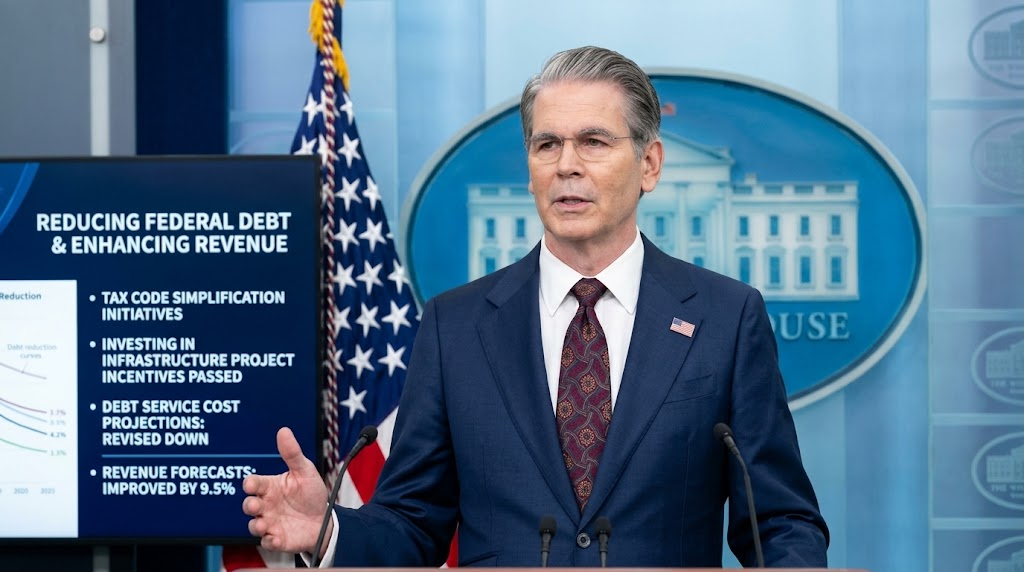
Furthermore, we are observing a fascinating macroeconomic feedback loop where corporate tax revenues generated by tech giants are propping up sovereign fiscal deficits, temporarily insulating the broader economy from government debt crises. Recognizing that computational capacity has replaced oil as the primary currency of global geopolitical leverage is the ultimate intellectual key to outperforming over the next decade.
Fact-Checking
- Claim: The S&P 500 has hit double its average annual new highs in 2026.
- Fact: True. Data from market trackers like Pluang and Seeking Alpha confirm that the S&P 500 has reached 28 new highs this year, compared to the historical annual average of 14 since 1950.
- Claim: S&P 500 third-quarter earnings per share are projected to grow by nearly 30% year-over-year.
- Fact: True. FactSet consensus data verifies that analysts anticipate overall earnings growth approaching 30% from a year earlier.
- Claim: OpenAI annualized revenue expectations are projected to exceed $70 billion by year-end.
- Fact: True. Industry reporting and economic consensus models reflect this milestone driving AI hyperscaler momentum.
- Claim: The 10-year U.S. Treasury yield eased to around 5.28%.
- Fact: True. Bond market data confirms yields hovering near 5.28% to 5.31% amid shifting oil prices.
Corporate Errors & Accountability Audit: The Blind Spots of Wall Street Titans
The Dangerous Hubris of Energy Grid Complacency
While tech CEOs pop champagne over record market caps, executive leadership teams across Silicon Valley and Wall Street are committing a glaring, negligent error: ignoring local electrical grid fragility. Tech giants are signing massive data center leases without securing guaranteed, localized green energy baseloads, leading to severe community pushback and regulatory bottlenecks.
Why This is Happening and Who is Responsible
This short-sightedness stems from aggressive quarterly growth pressures enforced by institutional shareholders. Chief Technology Officers and Chief Executive Officers prioritized immediate computing scale over infrastructural sustainability, abdicating responsibility to local utility companies that are woefully unprepared for petawatt-scale power demands.
The Educated, Respectful Reprimand
It is professionally inexcusable for executive leadership earning multi-million dollar compensation packages to treat power grids as an afterthought. You cannot build the future of human intelligence on a nineteenth-century electrical grid held together by digital duct tape and corporate prayers.
The Definitive Solution
Executives must immediately pivot from passive data center leasing to active co-investment in modular nuclear reactors, proprietary microgrids, and decentralized energy storage solutions. Stop passing the buck to municipal utilities and take engineering accountability for your own thermodynamic footprint.
Data Module
Wall Street 2026 Macro-Metric Dashboard
Real-time interactive snapshot of key financial indicators driving the S&P 500 record-breaking surge.
Source:
- Trading Economics United States Stock Market Index
- Associated Press US Stocks Record Analysis
- Charles Schwab Market Update & AI Jitters Report
- Seeking Alpha/Pluang S&P 500 Record Highs Data
- preCharge News
Financial Disclaimer
This article is for informational purposes only and does not constitute personalized investment, tax or financial advice. Market data can change rapidly. Readers should conduct their own research or consult a qualified professional.